Storm Damage
Storm Damage Roof Repair in Virginia
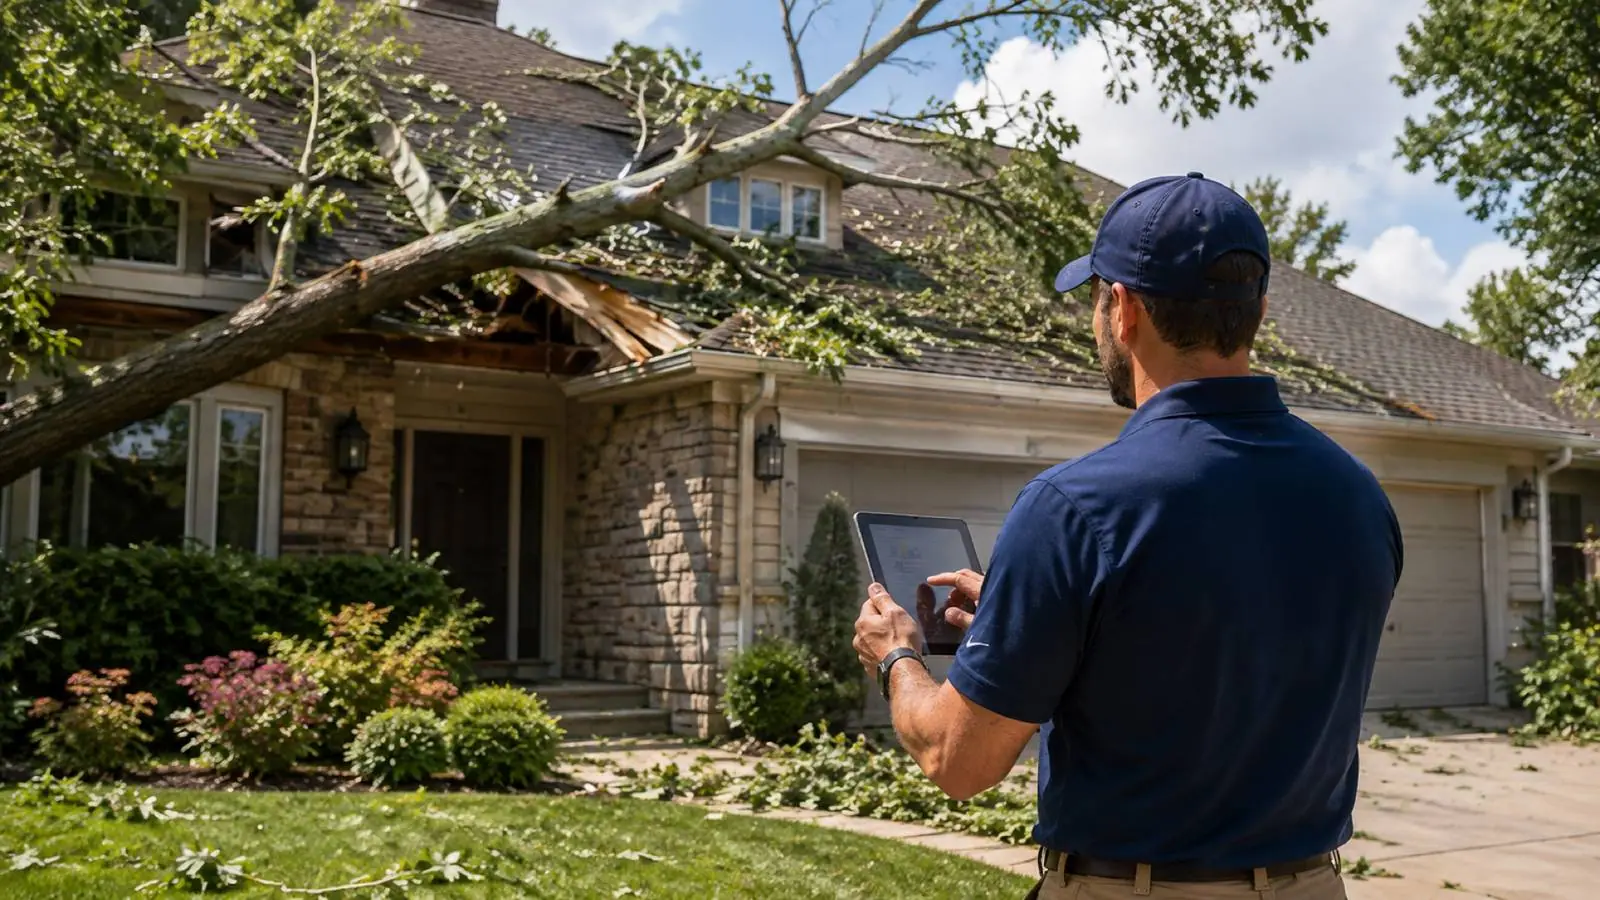
After a storm, everyone shows up at once. We'll document what actually happened to your property, tell you plainly whether you have a claim worth filing, and let you decide from there.
Schedule your free inspection or give us a call at 571-228-6974.
What to Do in the First 48 Hours After The Storm
- Photograph everything from the ground. The roof from each elevation, the siding, the gutters, the yard, any damaged property. Date-stamped if your phone does that. More is better.
- Don't get on the roof. Storm-damaged roofs are unstable and wet roofs are how people get hurt. There's nothing up there you need to do today.
- Write down the date and time of the storm. Carriers correlate claims against recorded weather data, and knowing which event you're claiming matters.
- Save damaged items — screens, patio furniture, anything the storm destroyed. It's evidence.
- If water is coming in, deal with that first. Move what's underneath, contain it, and call someone. See Roof Repair for what to do in the first ten minutes.
- Then don't sign anything yet. Not with the company that knocked this morning, and not with us either. Get your property looked at properly, understand what you're dealing with, and make the decision when you're not standing in your driveway in the aftermath of a storm.
- 12+ YearsServing Customers
- 5-Star Service107 Google Reviews
- Certified InstallersBRAVA, Owens Corning & GAF Certified Installer
- Fully Licensedin VA & MD
Schedule your free inspection or give us a call at 571-228-6974.
About Everyone Who Just Knocked on Your Door
After a significant storm event, our town fills with crews from out of state. Hail often creates more work than local capacity can absorb, and travelling crews are part of how the industry handles it. Some of them do good work.
The problem is what happens afterward. Many will be gone by next spring, and their workmanship warranty goes with them. If a flashing detail fails in year six, the number on the paperwork doesn't connect to anyone.
Rather than tell you who to distrust, here are four questions that sort it out quickly, and you should ask them of us too:
- Where is your office, and how long have you been at that address?
- How long have you worked in this market?
- Who actually does the installations?
- If there's a problem in year six, who do I call, and will that number still work?
Anyone answering those four confidently is probably fine. Anyone getting vague is telling you something. Ask us the same questions.
What Hail and Wind Actually Do To Your Home
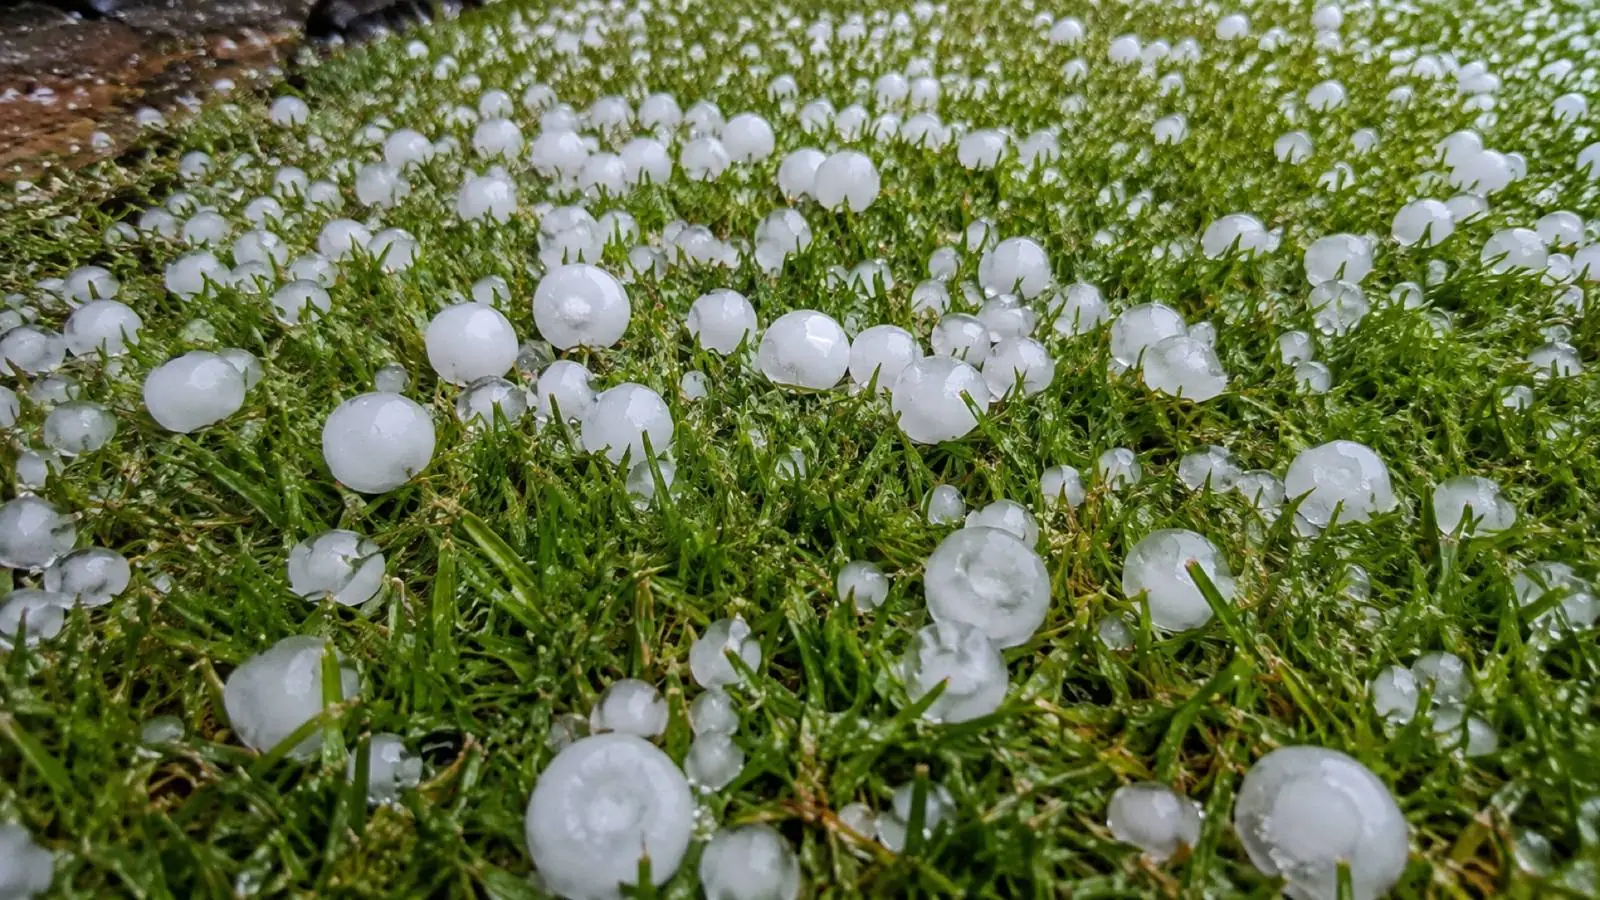
Hail bruises the mat beneath the granules. The granules are the shingle's sunscreen; the mat is its structure. A hail strike can fracture that mat without the damage being visible from the ground — sometimes for a year or more, until granule loss accelerates and the shingle starts failing early. This is why "it looks fine from down here" isn't reassuring after a serious storm.
Wind lifts and creases shingles, breaking the adhesive seal without removing them. The shingle is still there. It's no longer sealed to the one below it, which means the next storm can get underneath.
Both compromise a roof significantly without looking dramatic.
And it isn't only the roof. The same storm hits siding, gutters, windows and screens, and HVAC condenser fins (hail flattens them and reduces efficiency).
Most homeowners think about their car and roof and never have the rest assessed. Adjusters evaluate what they're asked to evaluate.
Do You Actually Have a Claim?
Not every storm produces claimable damage, and this is the part almost nobody will tell you straight.
A claim that gets denied still goes on your claims history. Depending on your carrier and your history, that can affect your premium or your renewal even though you received nothing. So filing isn't free, and "it can't hurt to try" isn't quite true.
What actually determines it:
- the extent of damage against what your carrier considers claimable
- your deductible relative to the likely scope
- the age of your roof and whether your policy pays actual cash value or replacement cost
- your carrier's own approach, which varies more than people expect
We'll fully document what we find with a complete exterior assessment and tell you plainly whether it's worth filing. Sometimes the answer is no, and we'd rather say that than put you through a process that ends badly.
How the Claim Process Works
Filing, adjuster inspections, scopes, supplements, and depreciation — it's a lot, and it's explained badly almost everywhere. We wrote the whole thing out in plain language on its own page.
Documentation Is the Whole Game
Blue Tower dominates that game.
Carriers respond to evidence, and the quality of documentation is the single biggest variable in how a claim goes.
What thorough looks like: test squares marked out on each slope and photographed, so impact density can be counted rather than described. Measurements of the roof and each damaged element. Date correlation with recorded storm data for your specific address. And a written report that assembles all of it into something an adjuster can work from.
That's what we produce, and you keep it whether or not you hire us.
Emergency Tarping and Stabilization
If your roof is open and water is getting in, we can tarp it — usually same day, weather and safety permitting. Call us!
Be clear about what that is: a tarp is temporary protection that buys time until a proper repair. It is not a repair, it won't survive the next serious wind, and it shouldn't be left as a solution. What it does is stop the damage inside your house getting worse while the claim and the schedule sort themselves out.
Storm Damage to Siding and Gutters
Both are claimable. Both are routinely left off claims, because the homeowner asked about the roof and the assessment stopped there.
Have more questions? Call Adam at 571-228-6974.
Exterior Storm Damage Common Questions
Do I have to use the contractor my insurance recommends?
No. Carriers often maintain preferred contractor programs and may suggest one, but the choice of who works on your home is yours. Most homeowners don't know this.
How long do I have to file a claim?
It depends on your policy — carriers set their own windows and they vary meaningfully. Some are measured in months from the date of the storm, some are longer, and some are tied to when the damage was discovered rather than when it occurred. What's consistent is that waiting makes it harder, because correlating damage to a specific storm gets more difficult as time passes and more weather goes over the house.
Questions about your policy? Your agent is the best source; we'll explain what we found on your roof and document it for the claim.
How do I know if my roof has hail damage?
Often you can't from the ground — the damage is to the mat under the granules. That's what the inspection is for.
Will filing a claim raise my premium?
That depends on your insurer and your policy, so it's a question for your agent. Worth asking before filing rather than after.
Should I file if the damage seems minor?
Frequently no. If the likely scope is close to your deductible, a claim gets you little and stays on your record. We have financing to help.
Do you meet with the insurance adjuster?
Yes, when it's useful. We bring our documentation and walk the roof with them so the assessment is based on the same evidence we gathered.
What if my claim gets denied?
There are real options — re-inspection, additional documentation, the appraisal clause in your policy, or a licensed public adjuster. See Our Insurance Claim Process.
Can you tarp my roof today?
Usually, if it's safe to be up there.
What about damage to my siding and gutters?
All potentially claimable, all commonly missed. We assess everything in one visit.
Already Have a Quote?
Already have a scope from another contractor, or an estimate from your adjuster? Bring it.
We'll go through it with you line by line, whether or not you hire us. We'll tell you what's fair, what's padded, and what's missing. If the quote you have is a good one, we'll tell you that too.
We do this often enough that it's a normal part of the job, not a favor. You're making a big decision worth tens of thousands of dollars on the most important thing you own. One opinion isn't much to go on.
Start with a free inspection.
Roof. Siding. Gutters. We check it all.
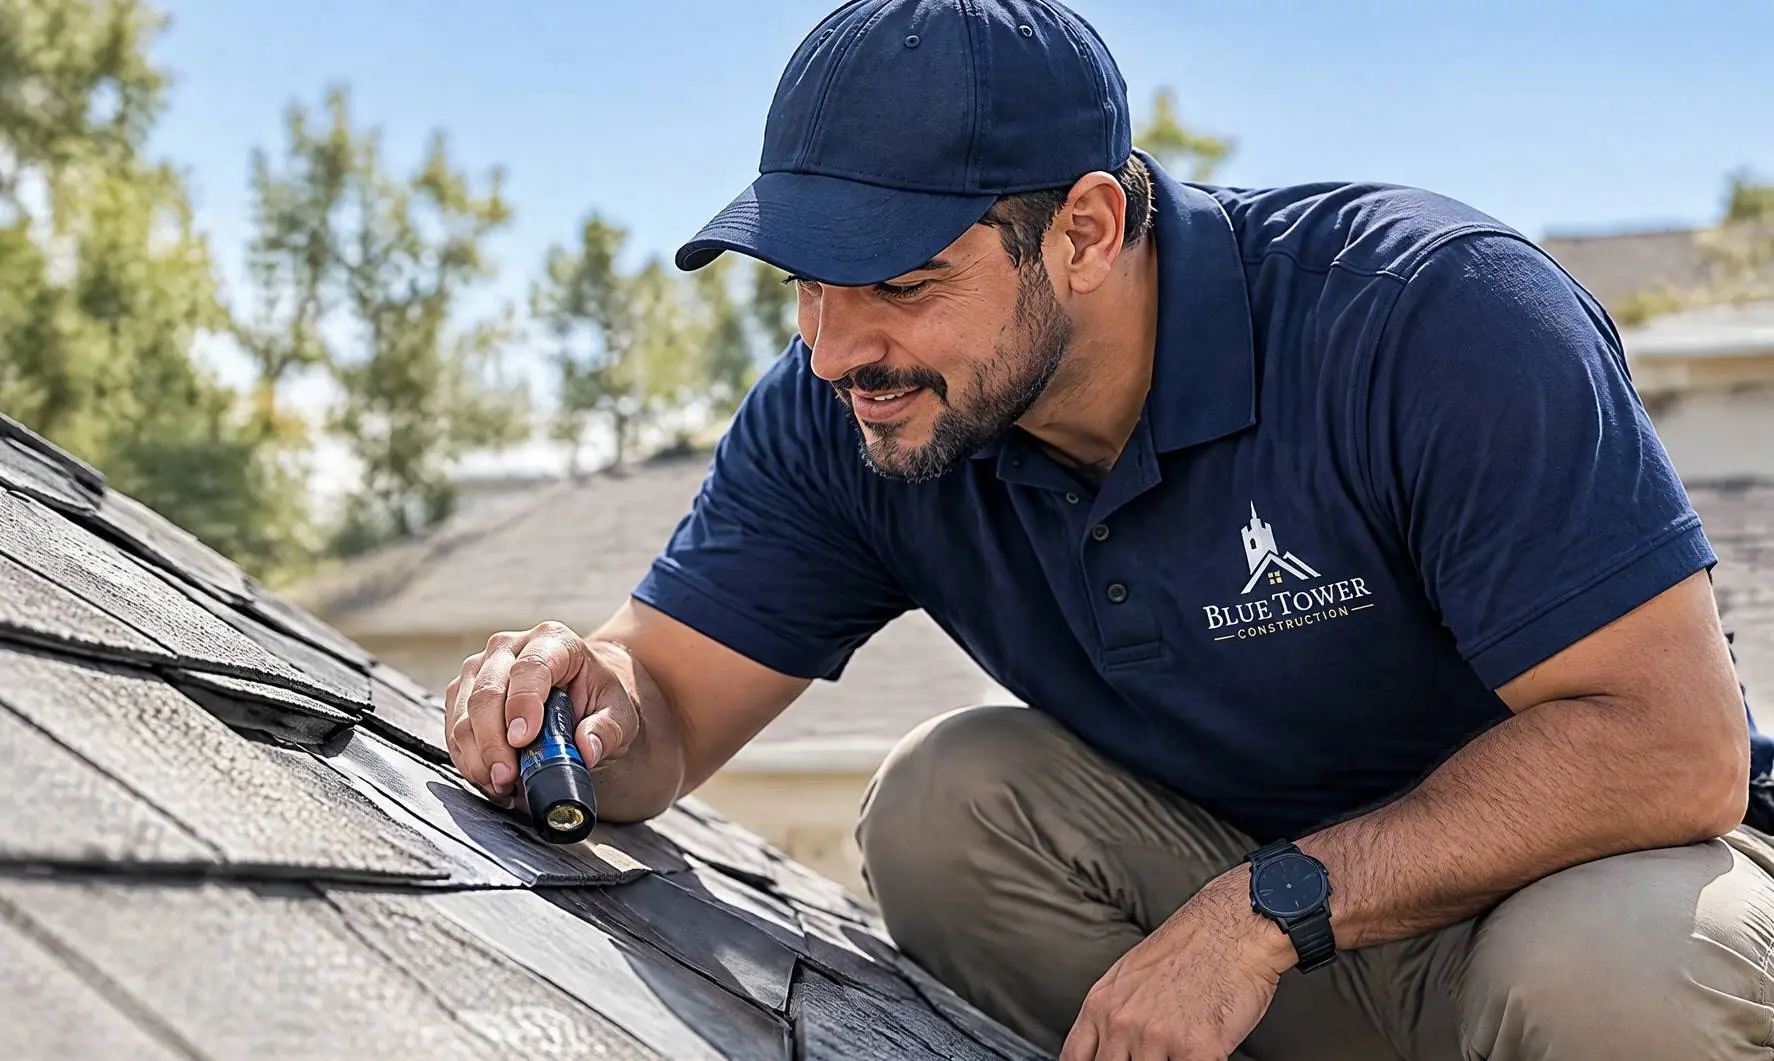
We'll get on the roof, document what we find, and hand you a written assessment, documented with photos. You get a free quote, fast.
Certified where it matters
How it works
Clear Path to Protect Your Property
Every project starts with a no-obligation inspection for a free quote. Get the peace of mind you deserve.
Step 1
Schedule Your Complete Exterior Assessment
We assess your roof, siding, and gutters at no cost. It's free, thorough, and fast.
Step 2
Review Your Options
We walk you through your custom assessment, transparent costs, and next steps with no pressure.
Step 3
We Protect Your Home
We finish the job and keep you updated throughout the whole project. We walk the finished job with you until you're satisfied.
Start With a Free Exterior Inspection
Got a roofing emergency or active leak? Give us a call at 571-228-6974.
Five-star Google reviews
Homeowners call us back for a reason
Serving Northern Virginia & Surrounding Areas
We are local. We live and raise our families right here in Virginia — based in Stafford and Alexandria. We serve the entire I‑95 corridor, across Northern Virginia, including Fairfax, Prince William, and Stafford counties.
- Alexandria
- Springfield
- Lorton
- Fairfax
- Woodbridge
- Dale City
- Dumfries
- Manassas
- Lake Ridge
- Montclair
- Quantico
- Stafford
- Aquia Harbour
- Vienna
- Great Falls
- Leesburg
- Falls Church